
Is it possible to retire early without millions in your bank account? Here are some practical tips to help you get started on your FIRE and financial planning journey.
Tired of Working? You’re Not Alone!
Monday morning. 6:30 AM.
Your alarm rings.
You hit snooze. Once. Twice. Maybe three times.
Then comes the usual routine. Get ready, drive to work, get stuck in the famous KL traffic jam, attend meetings, reply to emails, and work on endless Excel spreadsheets and PowerPoint presentations until it’s finally time to go home. 😵💫 🤢 😵💫
Sounds familiar?
Don’t get me wrong. Having a job is great. It pays the bills, puts food on the table, and hopefully leaves us some money for our next holiday.
But sometimes, don’t you just feel tired and bored? 🥱 😴
Tired of the 9-to-5 routine. Tired of asking permission to take leave. Tired of office politics, endless meetings, and all those rules and restrictions.
You start wondering: 🤔
“Is this really how I’m going to spend the next 20 or 30 years of my life?”
The FIRE Dream: Retire Early and Never Work Again!
Imagine this.
You wake up on Monday morning, enjoy a nice workout before having breakfast with your family, sip your morning kopi, and decide what you want to do for the rest of the day. 🧘🏽♀️
No alarm clock. No meetings. No annual leave applications.
Just time for your hobbies, your loved ones, and yourself. 😍
Sounds amazing, right?
That’s probably how many of us picture life after early retirement.
And there’s actually a name for this dream.
It’s called FIRE 🔥, which stands for Financial Independence, Retire Early.
But here’s the million-ringgit question.
How much money do you actually need to retire early in Malaysia?
If you’ve been researching early retirement or financial planning, I’m sure you’ve come across the famous 4% rule.
The Famous 4% Rule for Early Retirement
The 4% rule is one of the most popular guidelines used in retirement planning.
To estimate how much money you need, here’s a simple formula:
Annual Living Expenses ÷ 4% = Estimated Retirement Fund
Let’s say you’re spending RM5,000 every month.
That’s RM60,000 a year.
RM60,000 ÷ 4% = RM1.5 MILLION!
Yes, you read that correctly.
RM1.5 million! 😭 😱
In simple terms, the 4% rule suggests that you can start by withdrawing 4% of your retirement investment portfolio in the first year, then adjust that withdrawal amount for inflation in subsequent years.
That money is used to pay your bills and living expenses.
Essentially, your money is working for you!
Of course, the rule comes with assumptions about investment performance, inflation, and how long your retirement fund needs to last. It’s a starting point, not a guarantee that your money will last forever.
But one thing is clear.
We’re literally talking about millions of ringgit for early retirement!
Here’s what the numbers look like for different lifestyles.
| Monthly Expenses | Estimated FIRE Fund |
|---|---|
| RM3,000 | RM900,000 |
| RM4,000 | RM1,200,000 |
| RM5,000 | RM1,500,000 |
| RM8,000 | RM2,400,000 |
| RM10,000 | RM3,000,000 |
Note: These are simplified estimates based on the 4% rule, not guaranteed retirement amounts. Actual requirements depend on investment returns, inflation, retirement duration, and individual circumstances. Early retirees may need a more conservative approach.
Reality Hits: Where Am I Going to Find RM1.5 Million?
Aiyo 😤
Just when you were dreaming about retiring early, someone tells you that you need RM1.5 million.
For many ordinary Malaysians, that number feels like a mountain.
How long do we need to work to save that much?
10 years? 15 years? 20 years? 😫
Alamak. Sometimes we cannot even wait 10 months for our next holiday. How to wait another 20 years before enjoying life?
And here’s another thing that has been bothering me.
Let’s imagine you’ve finally achieved FIRE.
You have enough money. You don’t need to work anymore.
Congratulations!
So, what happens next?
You wake up. Have breakfast. Watch Netflix. Go shopping. Meet friends for coffee.
Repeat.
Sounds fantastic for the first few months.
But what about the next 10, 20, or 30 years?
Personally, I think the idea of retiring permanently and doing absolutely nothing sounds better on paper than in reality.
I have friends who have already achieved financial independence. Interestingly, some of them eventually found retirement boring.
Not because they missed their bosses or office meetings.
But because they missed having a purpose.
Something to work towards. Something to look forward to. Something that gives them a sense of achievement.
And that got me thinking.
What if we don’t actually want to stop working forever? What if we just want to break away from the same routine we’ve been living every single day?
Short-Term FIRE: Why Not Hit ‘Pause’ for Just 12 Months?
Here’s a different way to think about early retirement.
Instead of spending the next 20 years chasing RM1.5 million, why not break that big dream into smaller, more achievable goals? 🤑
What if you could afford to take 12 months off?
Or 24 months?
Or even 36 months?
I like to call this Short-Term FIRE, also known as mini-retirement.
It’s a simple idea.
Rather than becoming financially independent for the rest of your life immediately, you work towards having enough financial resources to take a meaningful break from your career.
You can use this period to travel, spend time with family, start a business, learn something new, or simply rediscover what makes you happy.
And when the break is over?
You can return to work, explore another career, continue building your business, or start planning your next mini-retirement.
After all, who says retirement has to be permanent?
Think of life as a book. 📖
Every chapter tells a different story.
Why must we wait until the final chapter to enjoy ourselves?
Sometimes, we just need to close one chapter and start another.
The beauty of Short-Term FIRE is that financial freedom might be much closer than you think.
Ask Yourself One Important Question
“What am I going to do with my freedom during Short-Term FIRE?” 🤔
This is probably one of the most important questions in your financial planning journey.
Because having money is one thing.
Knowing what to do with your time is another.
Some people want to travel around the world. 🌎
Some want to spend more time with their children while they’re still young.
Others want to care for their ageing parents, go back to university, improve their mental well-being, or pursue a passion they’ve put aside for years.
Everyone has a different reason.
And there’s no right or wrong answer.
Let Me Share My Personal Story
I’m 40 years old, and I’ve spent 14 years working in financial institutions.
Over the years, I’ve learned a lot, met wonderful people, and gained valuable experience.
But like many working Malaysians, there are times when I feel tired of corporate life.
It’s not that I don’t want to work anymore.
In fact, I still enjoy working, solving problems, and building something meaningful.
I just want the freedom to decide what I work on, when I work, and how I spend my time.
Lately, I’ve started to realise something.
I’ve spent so many years building my life around my career. Somehow, my job has become the centre of my life, and everything else revolves around it. 😫
But shouldn’t it be the other way around?
Shouldn’t our careers support the lives we want to live, rather than letting our careers decide how we live?
That’s something worth thinking about.
For me, one of my dreams is to build my own startup.
I want to create something of my own, enjoy more flexible working hours, and most importantly, spend more quality time with my family.
I don’t want my entire life to revolve around waiting for weekends, public holidays, and annual leave.
That’s my personal reason for pursuing financial independence.
Yours might be completely different.
Maybe you just need time to reset and recharge after years of stressful work.
That’s perfectly fine too.
The important thing is to know why you’re taking the break and what you want to achieve during that period.
Because taking a career break without a purpose is like booking a flight without knowing your destination.
You might enjoy the journey, but eventually you’ll wonder where you’re going.
Let’s Get Practical: How Much Money Do You Need for Short-Term FIRE?
If long-term FIRE feels out of reach, why not aim for Short-Term FIRE first?
Now comes the interesting part.
Let’s put aside that RM1.5 million retirement target for a moment.
Instead, let’s calculate how much money you actually need for a 12-month, 24-month, or 36-month career break.
Don’t worry. No complicated formulas here. 😍
Just five simple steps in financial planning that any Malaysian can follow.
Step 1: Calculate Your Monthly Expenses
First, let’s find out where your money goes every month.
Open Excel, grab a piece of paper, or use your favourite budgeting app.
List down all your expenses.
And I mean everything.
Your housing loan, car instalment, food, groceries, insurance, utilities, entertainment, and even your weekend shopping.
Here’s an example.
| Monthly Expenses | Amount |
|---|---|
| Housing Loan / Rent | RM2,000 |
| Food & Groceries | RM1,000 |
| Car Instalment / Transport | RM800 |
| Utilities / Internet / Phone | RM200 |
| Insurance | RM400 |
| Entertainment & Others | RM600 |
| Total Monthly Expenses | RM5,000 |
In this example, you need RM5,000 per month to maintain your lifestyle.
That’s RM60,000 a year.
Simple enough, right?
One small reminder: don’t forget expenses that only happen once or twice a year, such as road tax, car insurance, festive celebrations, holidays, and other commitments.
Include them in your budget too.
After all, these expenses won’t magically disappear just because you’ve stopped working!
Step 2: Calculate Your Current Monthly Income
Next, let’s look at how much money is coming in.
And more importantly, where that income is coming from.
Here’s an example.
| Monthly Income | Amount |
|---|---|
| Salary (after EPF and tax) | RM8,000 |
| Rental Income (after expenses) | RM300 |
| Dividends | RM200 |
| Side Income | RM500 |
| Total Monthly Income | RM9,000 |
Not bad!
You’re earning RM9,000 a month while spending RM5,000.
That means you’re already saving RM4,000 every month.
Good job!
But here’s something important.
When you’re planning for Short-Term FIRE, you need to separate your salary from other sources of income.
Why?
Because the moment you resign from your full-time job, that RM8,000 salary disappears.
However, your rental income, dividends, or side income might continue even when you’re not working full-time.
In this example, you have RM1,000 per month coming from sources other than your salary.
That’s a good start!
You’re already taking small steps towards becoming financially independent.
Of course, don’t forget that these sources of income aren’t always guaranteed.
Rental properties can be vacant, companies can reduce dividends, and side businesses can experience slow months.
So when doing your financial planning, always use realistic and conservative estimates. or prepare a buffer.
Step 3: Identify Your Income-Generating Assets
ow, let’s take a look at what you own.
Here’s an example of an investment asset portfolio.
| Investment Assets | Amount |
|---|---|
| Fixed Deposits | RM10,000 |
| Gold / Cryptocurrency | RM10,000 |
| Bursa Malaysia Shares | RM20,000 |
| Investment Property (Market Value Minus Outstanding Loan) | RM30,000 |
| Total Investment Assets | RM70,000 |
Maybe you have some fixed deposits.
Perhaps you’ve invested in dividend-paying shares.
Or maybe you have an investment property generating rental income every month.
These assets can potentially help fund your mini-retirement.
But here’s something important.
Not every asset you own can help pay your monthly bills.
For example, your own house might be worth RM800,000.
Sounds impressive, right?
But if your outstanding housing loan is RM790,000, your net equity is only RM10,000.
And if you’re living in that property without receiving any rental income, it doesn’t directly help pay for your groceries or daily expenses.
The same goes for your car.
So, when reviewing your assets for Short-Term FIRE, I suggest focusing on a few things:
- Income-generating assets: Assets that can continue providing income during your career break, such as rental properties or dividend-paying investments.
- Savings and investments: Money that you can withdraw, sell, or use to support your expenses during your break.
- Exclude personal-use assets: Your own home and car shouldn’t automatically be treated as available funds unless you actually plan to sell or monetise them.
- Treat EPF separately: EPF savings are generally intended for retirement and are subject to specific withdrawal rules. Only include amounts you are eligible to access during your planned break.
One more thing: property equity is not the same as cash in the bank. Property is illiquid asset.
Even if your investment property has RM30,000 in equity, you may not be able to access that money immediately without selling or refinancing the property.
Likewise, gold, cryptocurrency, and shares may fluctuate in value.
The objective is to understand how much usable money you truly have, not just how wealthy you appear on paper.
Step 4: Calculate How Much Money You Need for Short-Term FIRE
Now that we know your expenses, income, and assets, let’s put everything together.
First, decide how long you want your mini-retirement to last.
12 months?
24 months?
Or perhaps 36 months?
Using our earlier example, your monthly expenses are RM5,000.
Let’s calculate the total living expenses for each duration.
| Short-Term FIRE Duration | Living Expenses Required |
|---|---|
| 12 Months | RM60,000 |
| 24 Months | RM120,000 |
| 36 Months | RM180,000 |
See the difference?
Instead of immediately needing RM1.5 million to retire permanently, you may only need RM60,000 to cover 12 months of living expenses.
That’s a very different target, isn’t it?
Now, RM60,000 may still be a significant amount for some people.
But compared with RM1.5 million, it’s potentially a much more achievable goal. 🥰
And here’s something even more interesting.
Remember the RM1,000 monthly income from rental, dividends, and side income in Step 2?
If that income continues throughout your career break, it could help reduce the savings you need.
For example, a 24-month break would cost RM120,000 based on your expenses.
But if you consistently receive RM1,000 per month from other sources, that’s RM24,000 over two years. 🤑
Your estimated savings requirement could therefore fall to RM96,000.
However, for this guide, let’s be conservative and continue planning based on the full RM120,000.
Why?
Because we don’t want to depend entirely on income that might fluctuate or stop unexpectedly.
These figures also cover basic living expenses only.
If you plan to travel, study, or start a business, that requires a separate budget. 🤔
And importantly, think about what happens after your career break ends.
You may need several months to find another job or establish a reliable source of income.
So always keep an additional financial safety buffer.
Step 5: Calculate How Long You Need to Reach Your FIRE Target
Now comes my favourite part of financial planning.
Turning your FIRE dream into an actual timeline.
Let’s say you’ve decided to take a 24-month career break.
Based on our example, you need RM120,000.
But remember, you already have some investments.
From Step 3, your total investment assets are worth RM70,000.
Let’s assume you decide to use RM40,000 from your fixed deposits, gold, cryptocurrency, and shares to fund your Short-Term FIRE.
You leave your investment property untouched.
That means:
RM120,000 − RM40,000 = RM80,000
You still need another RM80,000.
Sounds like a lot?
Well, remember your monthly income and expenses from Steps 1 and 2?
You’re earning RM9,000 and spending RM5,000 every month.
That gives you a positive monthly cash flow of RM4,000.
If you save that RM4,000 consistently every month:
RM80,000 ÷ RM4,000 = 20 months
That’s it!
Under these simplified assumptions, you could reach your Short-Term FIRE target in 20 months.
Let’s summarise everything.
| Your Short-Term FIRE Plan | Amount |
|---|---|
| Target: 24-Month Career Break | RM120,000 |
| Existing Assets Allocated to FIRE | RM40,000 |
| Remaining Funding Gap | RM80,000 |
| Monthly Positive Cash Flow | RM4,000 |
| Time Needed to Reach Target | 20 Months |
Instead of thinking you need another 20 years to retire permanently, you now have a much more achievable milestone.
20 months of preparation for 24 months of freedom. 💃🏽
Sounds exciting, doesn’t it?
Of course, this calculation assumes your income and expenses stay the same, you consistently save RM4,000 every month, and your RM40,000 investment allocation is available at the value assumed.
It also excludes investment gains or losses, inflation, and any additional emergency reserves.
Most importantly, please don’t empty your entire savings account just to achieve Short-Term FIRE!
Make sure you have an emergency fund and enough protection for unexpected events, separate from the money you’ve set aside for your career break.
The point is not to spend every ringgit you have.
Short-Term FIRE is about buying yourself freedom while keeping your financial future secure.
Here’s a Little Financial Planning Secret: Expenses Are Like Fingernails
There’s something I always like to say.
Your expenses are like your fingernails.
They keep growing, and you need to trim them regularly.
Think about it.
When we first started working, maybe earning RM3,000 a month was enough.
Then our salary increased.
Great news!
But somehow, our expenses increased too.
We upgraded our phones, bought a nicer car, subscribed to more streaming platforms, and started eating at more expensive restaurants.
Before we realised it, our monthly expenses had grown together with our salary.
Sounds familiar? This is lifestyle inflation. 😵💫
Now, I’m not suggesting you should stop enjoying life.
Please lah.
What’s the point of working so hard if you cannot enjoy your favourite nasi lemak, teh tarik, or occasional holiday?
But there’s a difference between spending money on things that genuinely make you happy and spending money simply out of habit.
So here’s my advice.
Review your expenses every month, just like trimming your fingernails.
If your monthly expenses are higher than your income, that’s your first warning sign.
Time to take a closer look.
Can you reduce unnecessary subscriptions?
Can you cut down on impulse purchases?
Can you avoid upgrading your car just because your salary increased?
You may be surprised by how much you can save.
Let’s say you’re able to reduce your monthly expenses by RM500.
That’s RM6,000 a year. 🤑
And here’s the best part.
You’re not only saving an extra RM500 every month. You’re also reducing the amount of money you’ll need during your mini-retirement.
For a 24-month break, spending RM500 less each month means you’ll need RM12,000 less.
Remember our earlier example?
Your original Short-Term FIRE target was RM120,000.
By reducing your monthly expenses from RM5,000 to RM4,500, your target drops to RM108,000.
Meanwhile, your monthly savings increase from RM4,000 to RM4,500.
Using the same RM40,000 starting fund, you could now reach your target in approximately 16 months instead of 20 months.
Just by trimming RM500 from your monthly expenses, you could bring your FIRE journey forward by around four months!
Not bad for a little trimming, right?
The objective isn’t to become extremely frugal.
It’s to make sure your money is being spent on things that actually matter to you.
Because the less money you need to maintain your lifestyle, the faster you can achieve financial freedom.
Don’t Wait Until 60 to Start Living
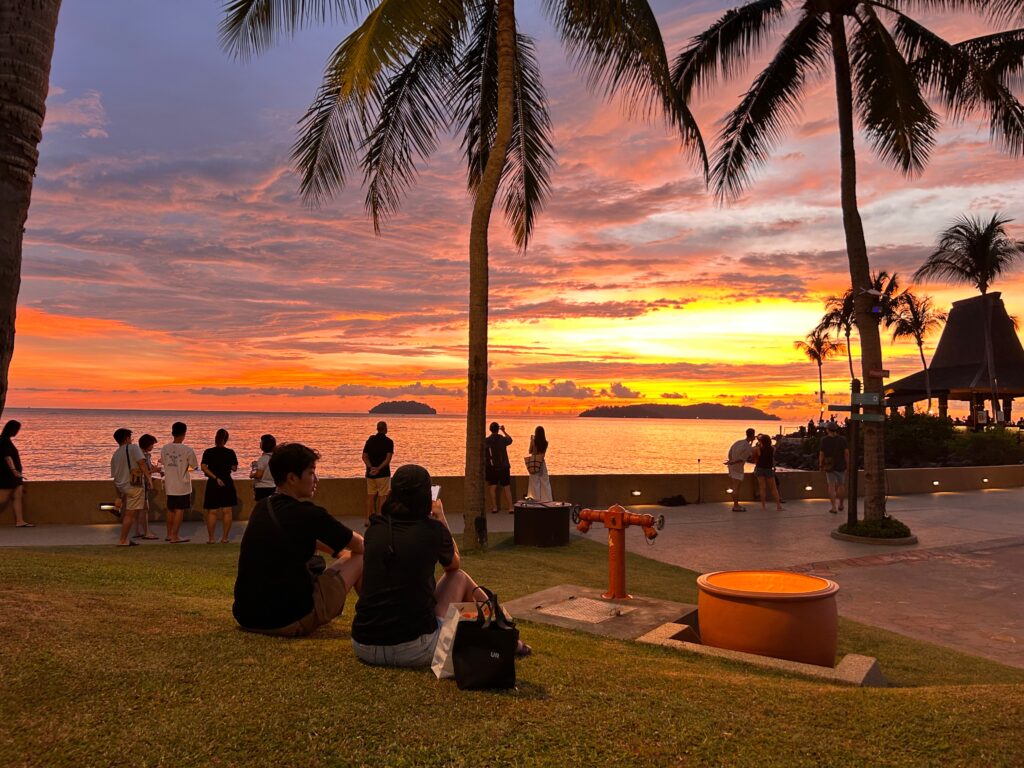
We often think of retirement as something that happens at the end of our working lives.
Work hard for 30 or 40 years.
Save as much money as possible.
Then finally, when we’re 60 or older, we can start enjoying life.
But what if there’s another way?
What if we could enjoy some of that freedom earlier?
Travel while we’re still energetic.
Spend more time with our family while our children are still young.
Pursue a business idea we’ve been dreaming about for years.
Or simply take a break, slow down, and appreciate the little moments in life. ☕️
Maybe retiring early in Malaysia doesn’t necessarily mean quitting work forever.
Maybe it simply means having the financial freedom to choose what you want to do next.
And that’s exactly what I hope to share through JomFIRE.
I believe everyone deserves the opportunity to work towards financial independence, regardless of whether you’re earning RM3,000, RM10,000, or RM30,000 a month.
You don’t necessarily need millions before you can start making meaningful changes to your life.
Sometimes, all you need is a clear goal, a realistic plan, and the courage to start.
Because life isn’t just about making a living. It’s also about making a life.
And here’s one final question I’d like to leave you with.
If you could afford to take 12 months off work without worrying about money, what would you do?
Travel around the world? Start your own business? Spend more time with your family?
Or simply wake up every morning and enjoy a cup of kopi without rushing anywhere?
Whatever your answer is, maybe that’s the FIRE worth working towards.
Jom plan. 💰 Jom live. 💃🏽 JomFIRE! 🔥
Need a Little Help Planning Your Own FIRE Journey?
Not sure how much money you need to retire early in Malaysia?
Or wondering whether you have enough savings to take a 12-month or 24-month career break?
At JomFIRE, we believe financial planning should be simple, practical, and accessible to everyday Malaysians.
Whether you’re aiming for permanent financial independence or simply planning a short-term mini-retirement, we’re here to help you understand your finances and explore your options.
For personalised financial planning assistance, reach out to us at [email protected].
Our financial planning professionals can assist you for a modest fee. 🙇🏻 🙇🏻♀️
Your financial freedom journey starts with one simple step. JomFIRE! 🔥

Leave a Reply